ASEAN is developing instant cross-border payment capabilities through interconnected fast payment systems, unified QR code standards, and coordination among central banks. These initiatives are transforming the region into a near-real-time cross-border payments network — ASEAN digital payments were valued at $806 billion in 2022 and are projected to reach $1.2 trillion by 2025.
Key milestones between 2021 and 2024 include the 2021 linkage of Thailand’s PromptPay and Singapore’s PayNow, the 2023 Malaysia–Singapore linkage of DuitNow and PayNow, and the expansion of QR code cooperation across ASEAN countries. ASEAN leads developing regions in retail cross-border connectivity. These advances have reduced remittance costs, supported tourism and e-commerce, and advanced regional integration. This paper outlines specific schemes, the role of central banks, associated risks, crypto asset connectivity, and the outlook toward 2030.
Development of ASEAN Digital Payments Since the 2010s
Before 2010, Southeast Asia relied heavily on cash and slow correspondent banking settlement for cross-border payments; payment systems were fragmented and international settlement often took several days.
The past decade has changed that landscape. Domestic instant payment rails have been launched across the region:
-
Thailand PromptPay (2017) — instant payments now account for 77% of domestic transactions in Thailand
-
Singapore FAST (2014) and PayNow (2017)
-
Malaysia DuitNow (2018)
-
Indonesia BI-FAST (2021)
-
Philippines InstaPay (2018)
-
Vietnam NAPAS 24/7
Fintech innovation has driven rapid growth in ASEAN digital payments, with consumers shifting from card-centric habits toward account-to-account and QR code payments. Mobile wallet and instant payment usage have expanded rapidly across the region. Half of the top ten countries by digital wallet penetration are from ASEAN; digital wallets are also driving cross-border payments among ASEAN countries. Cambodia’s account ownership rose from 3% in 2011 to 60%, demonstrating how adoption can change substantially in a short period. These domestic rails have become the foundation for current cross-border digital payment and regional payment connectivity initiatives.
Flagship Cross-Border Instant Payment Linkages in ASEAN
Cross-border Fast Payment System (FPS) linkages connect domestic fast payment systems across countries, allowing users in one country to remit to or pay merchants in another country as if making a local transfer—typically using proxy identifiers such as mobile numbers, achieving near-real-time settlement at low cost.
Since PromptPay and PayNow were linked in April 2021, they have enabled low-cost mobile transfers between Thailand and Singapore. The linkage has a daily limit of SGD 1,000 and typically settles in under one minute. By mid-2022, Thailand’s PromptPay processed over 65,000 cross-border transactions per month via this channel, and that figure has continued to grow; in steady state, the linkage can exceed 65,000 transactions per month.
Other bilateral linkages include:
-
PayNow–DuitNow (Singapore–Malaysia, launched March 2023)
-
DuitNow–PromptPay (Malaysia–Thailand)
-
Planned expansion to Indonesia's BI-FAST and the Philippines' InstaPay
Since 2021, the number of cross-border payment linkages in ASEAN has grown significantly. These systems typically adopt the ISO 20022 message standard and use common standards for identity alias management, enabling interoperability and competitive foreign exchange pricing.
For example: a Thai worker in Singapore sends funds to Thailand using the recipient’s Thai mobile number. The transfer completes in under a minute, fees are far lower than traditional remittance services, and the recipient receives Thai baht directly.
Regional QR Code Payment Connectivity and Everyday Use Cases
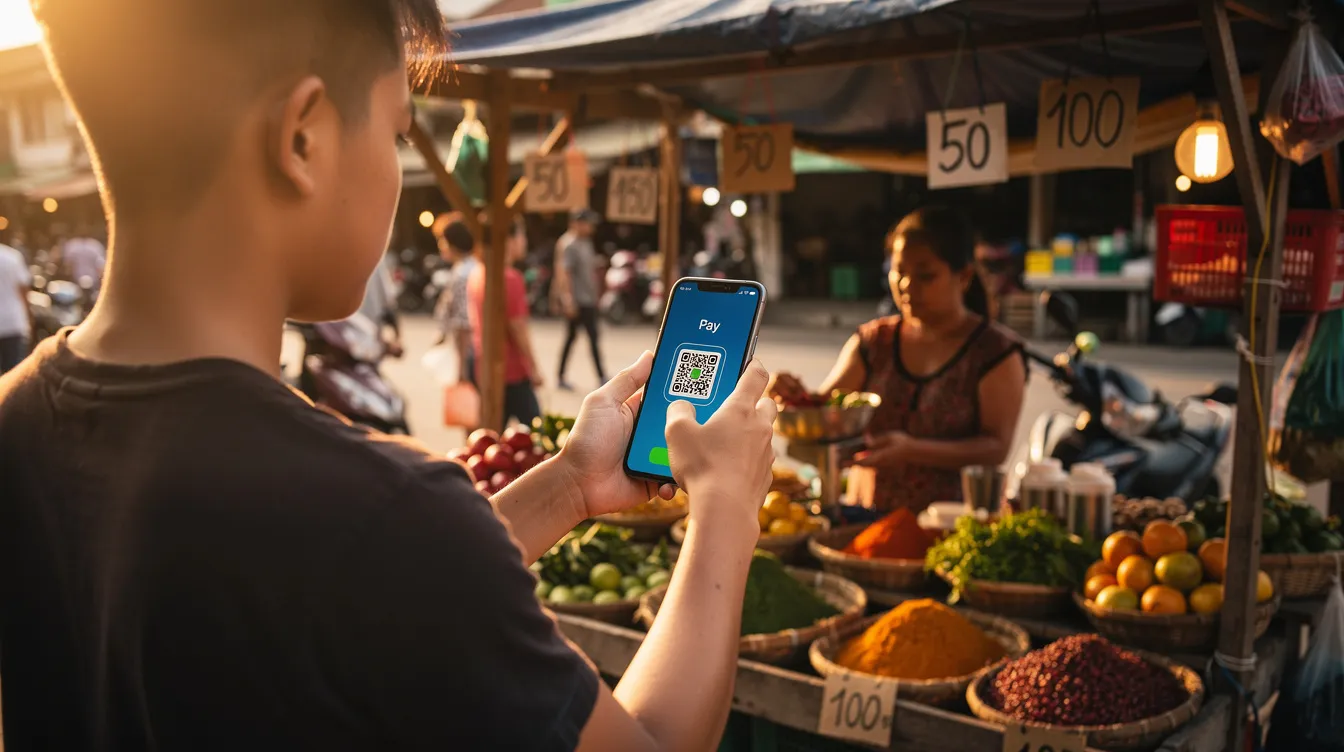
Beyond account-to-account cross-border transfers, ASEAN is promoting QR interoperability in retail and tourism. Bilateral QR linkages now cover Thailand–Malaysia, Thailand–Cambodia, Indonesia–Thailand, Indonesia–Malaysia, and routes such as Singapore–Thailand under broader ASEAN QR payment connectivity frameworks.
For example, a traveler from Malaysia to Bangkok can scan a merchant’s local QR code using her DuitNow app. The backend automatically handles currency conversion, the merchant receives Thai baht instantly, and the traveler pays in ringgit—without a card terminal or cash exchange.
Benefits for merchants and businesses include:
-
Fees lower than card network commissions
-
Instant payment confirmation
-
More transparent foreign exchange handling
-
Financial inclusion for micro and small enterprises without POS terminals
Combined with digital identity and interoperable banking services, QR payments can further digitize cross-border commerce in ASEAN and make QR payments accessible to more cross-border merchants.
Role of Central Banks and Regional Policy in Payment Connectivity
Central banks—including MAS (Singapore), BOT (Thailand), Bank Indonesia, BNM (Malaysia) and BSP (Philippines)—are actively promoting payment connectivity. Their coordination determines the regulatory frameworks, technical standards and supervisory approaches for cross-border linkages.
Key policy milestones include:
-
The ASEAN Leaders’ Declaration: advancing regional payment connectivity and promoting local currency transactions (May 2023)
-
MoUs among central banks on regional payment connectivity (2022–2023)
-
ASEAN aims to finalize the Digital Economy Framework Agreement by 2025, harmonizing rules on digital trade and digital payments
Project Nexus is an initiative of the BIS Innovation Hub designed to standardize connections between domestic payment systems through a shared multilateral platform. Initial participants included Thailand, Singapore, Malaysia, the Philippines and India. In 2025, a legal entity called Nexus Global Payments was established to move the project toward implementation.
Local currency settlement frameworks aim to reduce ASEAN’s reliance on the US dollar for intra-regional settlement. Increasingly, transactions in the region are being settled in local currencies rather than the dollar, and bilateral agreements among financial institutions are putting this shift into practice. While promoting such innovations, central banks must also balance AML, data protection, foreign exchange regulation and operational resilience requirements.
Impact on Financial Inclusion, SMEs, and Regional Integration
Cheaper and faster cross-border payments can significantly advance financial inclusion and inclusive growth. Migrant workers directly benefit from lower remittance costs when they send funds home using instant cross-border payments instead of traditional remittance services.
For SMEs, instant payment solutions can alleviate B2B payment pain points—speeding up invoicing and collections, reducing dependence on correspondent banking settlement, improving cash flow and enabling participation in regional e-commerce supply chains. For example, an SME in Bangkok selling to Singapore can receive payment via PromptPay–PayNow in about a minute.
But gaps remain. ASEAN’s access to digital financial services is uneven. Adoption of e-money accounts varies significantly across countries and is much higher in urban areas than rural. Smartphone penetration, financial literacy, cross-border identity verification challenges and persistent cash preference in some areas constrain the reach of digital payments for financial inclusion.
Risks, Challenges, and Policy Trade‑Offs in Cross‑Border Digital Payments
Faster and cheaper cross-border payments introduce new risks. As instant digital payments spread, cyber security risks increase, including attacks on payment system infrastructure, data breaches, and settlement risks across multiple time zones and jurisdictions.
ASEAN cross-border payments also face regulatory fragmentation. Cross-border B2B payments encounter differing regulatory thresholds across jurisdictions—varying AML requirements, data localization rules, consumer protection standards and dispute resolution mechanisms. Exchange rate volatility further heightens foreign exchange risk for businesses and payment service providers.
Wholesale‑level integration also faces structural barriers, including uneven technical readiness among national payment system operators. Without multilateral initiatives like Project Nexus, the region could fragment into a series of bilateral linkages lacking common standards and a consistent user experience.
User education is critical. As digital payments scale, governments and financial institutions need to help users understand fees, FX markups and fraud prevention measures, especially for vulnerable groups with low digital and financial literacy.
Crypto, Stablecoins, and Web3 in ASEAN Cross‑Border Finance
Most retail cross-border payments in ASEAN still run over bank and central bank‑operated rails, but crypto and stablecoins are emerging as alternative channels, particularly among freelancers, Web3 workers and businesses transacting in digital goods.
Dollar‑pegged stablecoins or regional currency stablecoins can provide 24/7 cross-border settlement capabilities, not constrained by traditional banking hours. Singapore established a regulatory framework for stablecoin issuers in 2023–2024; other ASEAN countries are still assessing the associated risks.
ASEAN is also exploring central bank digital currencies (CBDCs) for cross-border transactions and considering wholesale and retail CBDC pilots. In the future, smart contracts and tokenized deposits could interconnect with fast payment systems to enable programmable cross-border money flows.
Key risks remain: volatility of non‑stable assets, smart contract vulnerabilities, custody and private key management risks, and regulatory uncertainty across jurisdictions. Without integration into the regulated financial system, these channels may lack legal protections or merchant acceptance.
How Gate Can Help with ASEAN Digital and Cross‑Border Payments
Individuals and businesses seeking to expand cross‑border value transfer channels in ASEAN and neighboring regions can consider crypto and stablecoin markets. In supported jurisdictions, [Gate Exchange] users can access crypto and certain stablecoin markets around the clock, providing additional cross‑border value transfer options where legally permitted.
Users who prefer self‑custody can use [Gate Web3 Wallet] to manage supported assets when interacting with Web3 payments or decentralized finance applications. [Gate Pay] enables payments to merchants or peers using compatible digital assets, subject to user eligibility, jurisdictional restrictions and merchant acceptance.
Before using crypto assets for cross‑border payments, users should evaluate fees, the availability of on/off‑ramp channels, and local regulatory and compliance requirements. Product features and availability may vary by jurisdiction.
Future Outlook for ASEAN Payment Connectivity and Cross‑Border Finance
By 2030, ASEAN aims to be a highly integrated digital economy with seamless cross‑border payment connectivity. Broader participation in multilateral platforms like Project Nexus, expansion of QR networks, and CBDC pilots for cross‑border settlement are among the anticipated developments.
Progress will depend on regulatory coordination, investments in cyber security and the adoption of interoperability standards (such as ISO 20022 and a common QR code format). As infrastructure matures, convergence may occur between bank rails, tokenized deposits and regulated stablecoins, reshaping how cross‑border transactions operate. Both the private sector and governments will play important roles.
Progress can be tracked by following policy statements from ASEAN central banks and market data on cross‑border payment volumes. Supported assets and market information are viewable on Gate, subject to regional availability.
Conclusion and Key Takeaways
ASEAN is transforming fragmented domestic digital payment systems into a more unified cross‑border payment network through fast payment linkages, QR interoperability and central bank cooperation. The benefits—faster settlement, lower costs, closer regional cooperation and broader financial inclusion—are already visible, with the region processing hundreds of billions in digital payment value annually.
Risks related to regulation, cyber security and inclusion require sustained public‑private collaboration. Users choosing cross‑border solutions should compare options across bank channels, fintech providers and regulated digital asset platforms.
FAQ
What is the PromptPay–PayNow linkage?
The PromptPay–PayNow linkage connects Thailand’s PromptPay with Singapore’s PayNow as a cross‑border instant payment connection that began in 2021. Users can send up to SGD 1,000 per day to a recipient using the recipient’s mobile number, and transfers typically complete within a minute. It is one of the first fast payment system linkages launched in ASEAN.
Are stablecoins used for cross-border payments in ASEAN?
Stablecoins are emerging as a complementary channel, particularly among freelancers and digital businesses. Singapore has established a regulatory framework for stablecoin issuers. However, most retail cross‑border payments in ASEAN still occur over bank‑operated rails, and stablecoin use faces regulatory uncertainty and custody risks.
What is Project Nexus?
Project Nexus is an initiative of the BIS Innovation Hub that aims to connect domestic instant payment systems via a shared multilateral platform standard. Initial participant central banks included those of Singapore, Thailand, Malaysia, the Philippines, Indonesia and India. In 2025, a legal entity was formed to advance the project toward implementation.
* The information is not intended to be and does not constitute financial advice or any other recommendation of any sort offered or endorsed by Gate.

















